AI Infrastructure & Markets
Nvidia’s Quarterly Profit Tops $26 Billion: Is the Token Economy Starting to Pay Off?
Nvidia’s results show that AI infrastructure demand remains powerful. The bigger question is whether downstream companies can turn rising token consumption into durable business returns.
Nvidia has delivered another powerful quarter.
Based on the quarterly figures cited in the original report, revenue reached roughly $46.7 billion and net income exceeded $26 billion, with the data-center business remaining the primary growth engine. The company also issued a higher revenue outlook for the following quarter, suggesting that demand for accelerated computing from major technology companies, cloud providers and AI labs remains strong.
For U.S. investors, the significance goes beyond how much money Nvidia made. The results provide evidence for a broader industry thesis: generative AI is moving from demonstrations into infrastructure spending, while tokens are evolving from an internal unit of model activity into a link between computing investment and commercial revenue.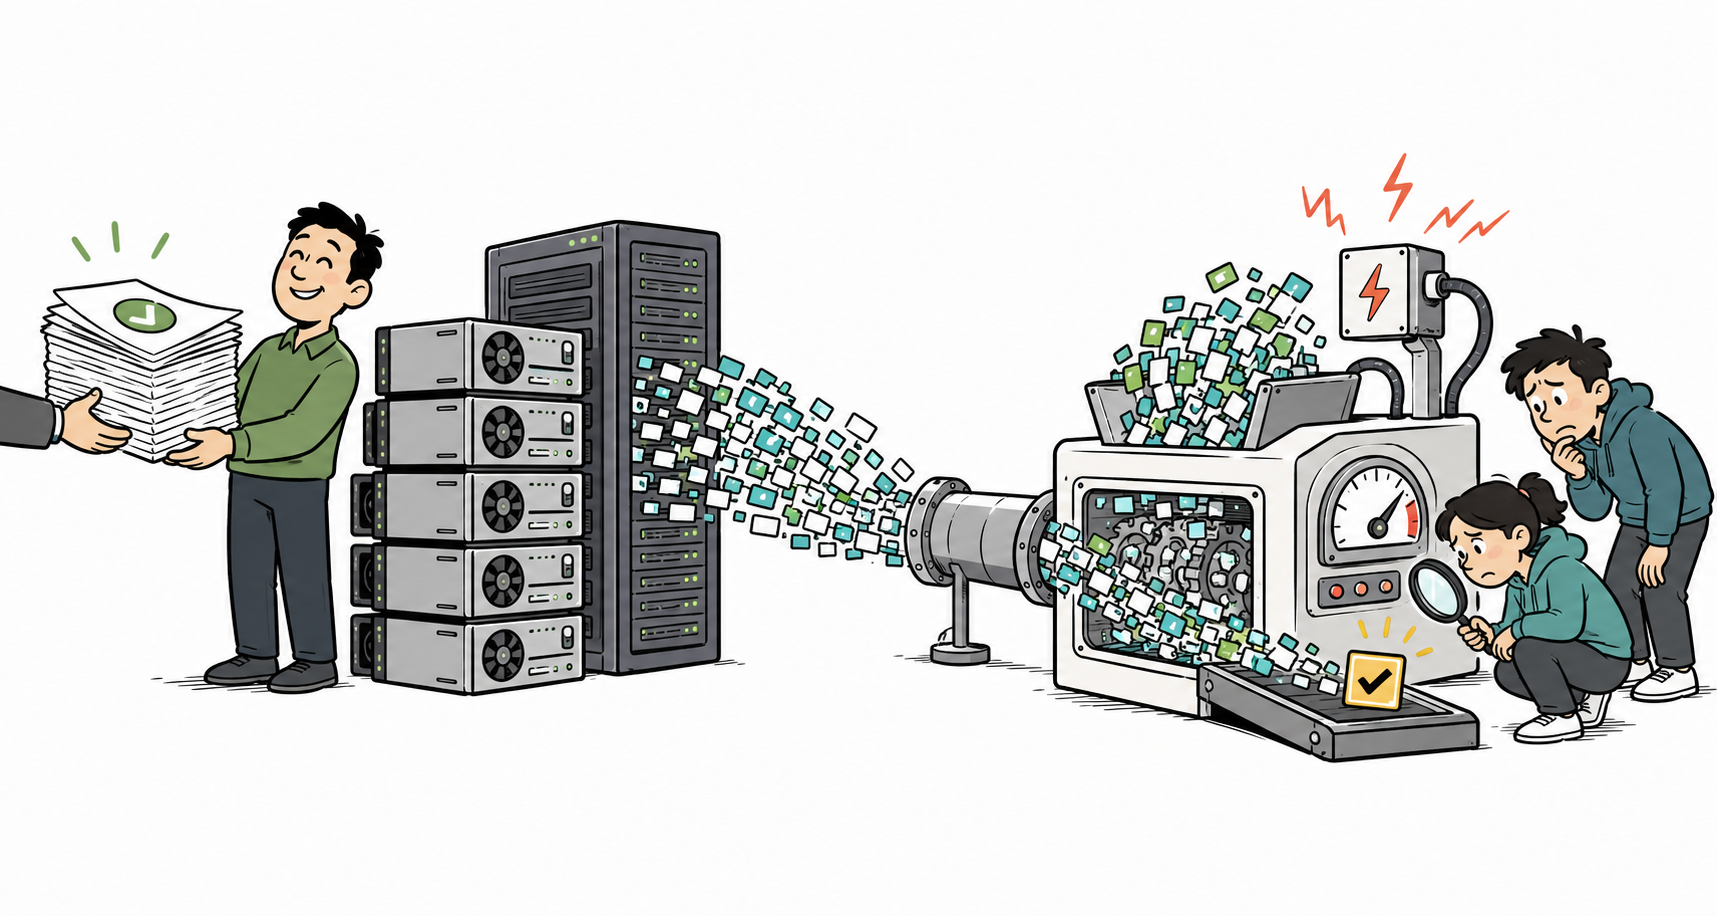
The question that matters is whether GPUs, electricity and data-center capacity can consistently be converted into useful, billable tokens that generate measurable business outcomes.
What Does a Gross Margin Above 70% Tell Us?
Nvidia’s profitability remains remarkable. A quarterly gross margin around 70% indicates that the company still possesses substantial pricing power in AI accelerators.
Several factors help explain it:
A full-stack platform
The GPU is only one component. Nvidia also sells high-speed interconnects, networking, server systems, the CUDA software ecosystem and enterprise development tools. Customers are purchasing an integrated platform for training and deploying models faster.
Constrained advanced capacity
Cloud providers and model developers must secure not only chips but also electricity, facilities, networking and cooling. Few suppliers can combine leading hardware with a mature software ecosystem.
Rapidly growing inference demand
Training large models still requires concentrated computing power, but every request made through search, productivity software, customer service, coding tools, advertising systems and enterprise agents consumes additional tokens. Inference can turn a one-time model-building expense into recurring infrastructure demand.
That is why investors are paying closer attention to tokens per watt and inferences per dollar—not merely a chip’s theoretical performance.
The Token Economy Is Moving From Concept to Revenue
The token economy can be understood in simple terms: computing power, electricity, data and models work together to produce tokens, and applications convert those tokens into services for which customers are willing to pay.
Nvidia operates primarily at the upstream end of this value chain. It sells accelerated-computing platforms to cloud providers, model developers and enterprise data centers. Cloud companies charge customers for time, computing capacity or token usage. Application companies then earn revenue from subscriptions, API calls, advertising, automation services or completed tasks.
The Emerging Flywheel
- Businesses and consumers increase their use of AI.
- Models must generate more tokens.
- Cloud platforms need more inference capacity.
- Data centers buy additional GPUs, networking and power capacity.
- Lower inference costs make more AI applications economically viable.
Nvidia’s strong data-center revenue indicates that this flywheel is moving quickly at the infrastructure layer. Whether it becomes a sustainable economic system depends on whether downstream customers can earn sufficient returns from AI services.
If a company spends millions of dollars deploying agents without improving productivity, reducing costs or increasing sales, higher token consumption is simply a larger expense. The token economy truly pays off only when tokens complete real tasks and produce measurable results.
The Shift From Training to Inference Changes the Market
Much of the AI infrastructure investment of recent years focused on training larger models. Training is generally a concentrated, large-scale computing job that requires many high-end GPUs to operate together.
Inference is becoming more important in the agent era. An agent that independently retrieves information, operates tools, writes code and checks its own work may call a model dozens of times to complete one task. It produces far more tokens than a conventional question-and-answer interaction and imposes stricter requirements for latency, stability and cost.
That changes how data centers must be built:
- ✓Training clusters emphasize extremely high parallel computing performance.
- ✓Inference platforms prioritize response time, throughput and continuous availability.
- ✓Enterprise agents require stronger data isolation, access controls and auditing.
- ✓Different workloads may run on GPUs, CPUs or specialized accelerators.
- ✓Smaller models, quantization, caching and routing become important tools for reducing token costs.
The next competition will not be only about who owns the most GPUs. It will be about who can produce useful tokens with the lowest cost, lowest latency and highest reliability.
China Is Both an Opportunity and a Source of Uncertainty
For Nvidia, China remains impossible to ignore—but difficult to forecast.
U.S. export controls restrict sales of advanced AI chips to China. Nvidia has designed products intended to comply with those rules, but regulatory approval, customer demand and the progress of domestic alternatives all affect actual revenue.
Chinese technology companies are accelerating the development of domestic AI hardware and software. Huawei and others continue to invest in chips, servers, networking and development tools. For U.S. readers, this is not only a question of how much market share Nvidia may lose. It also raises the possibility that the global AI supply chain will split into increasingly separate technology ecosystems.
If the United States and China rely on different chips, software stacks and model infrastructure, global token production may become more fragmented. American companies must navigate export restrictions and market access, while Chinese companies face challenges in chip supply, software maturity and energy efficiency.
China-related sales should therefore be viewed as potential upside rather than guaranteed growth.
The Real Test: Can Customers Earn an Adequate Return on AI?
Nvidia’s management remains optimistic about future AI infrastructure investment and has repeatedly argued that global data centers are shifting from general-purpose to accelerated computing.
There is considerable evidence for that transition. Major cloud providers continue to raise capital spending, and enterprises are experimenting aggressively with generative AI and agents. But the faster spending grows, the more investors will demand proof of returns.
U.S. investors should watch several signals:
| Cloud revenue | Can Microsoft, Amazon, Google and Meta continue increasing AI-related revenue? |
| Enterprise adoption | Are customers moving from pilot projects to large-scale deployment? |
| Inference economics | Can unit costs decline fast enough to offset rising token usage? |
| Business outcomes | Do AI applications improve productivity and generate dependable cash flow? |
| Physical constraints | Will electricity, cooling and construction become the next bottlenecks? |
| Competition | Will rival chips and customer-designed accelerators pressure Nvidia’s margins? |
If downstream companies cannot demonstrate value from AI investment, GPU purchases may eventually slow. If AI applications begin generating revenue at scale, token demand could become a durable growth metric much like data traffic in cloud computing.
High Margins Will Not Last Forever
Nvidia’s current margins reflect product leadership, tight supply, software advantages and scale. None of those conditions is guaranteed to remain unchanged.
AMD is advancing a new generation of AI accelerators, while Google, Amazon, Microsoft and Meta continue developing custom chips. As alternatives expand, supply improves and customers gain bargaining power, Nvidia’s pricing power may gradually come under pressure.
AI infrastructure also faces energy constraints. Large data centers require enormous amounts of electricity, and some projects are already limited by transmission capacity, generation supply and lengthy permitting. Chips can be manufactured faster than power infrastructure can be expanded.
The next stage of competition may therefore extend from chip availability to system-wide energy efficiency. Platforms that generate more useful tokens with less power will be better positioned to win orders from cloud providers and enterprise customers.
The Token Economy Is Paying Off—But It Has Not Yet Passed the Full Test
Nvidia’s quarterly performance shows that demand for AI infrastructure remains strong and that token growth can already be converted into real revenue for chips, networks and data centers.
But there is a long road between rising infrastructure revenue and durable profitability across the AI industry. Upstream suppliers are already earning substantial returns. Whether downstream application companies can do the same will determine how long the investment cycle lasts.
In the coming years, the market will look beyond model parameters, GPU counts and total token volume. It will focus increasingly on how many useful tasks each dollar can complete, how many valuable tokens each watt can produce, and how much revenue or cost savings those tokens ultimately create.
The token economy has begun to pay off—but so far, infrastructure suppliers are collecting the clearest returns. Enterprise applications, AI agents and end-user demand still have to prove that the system can be sustainable.